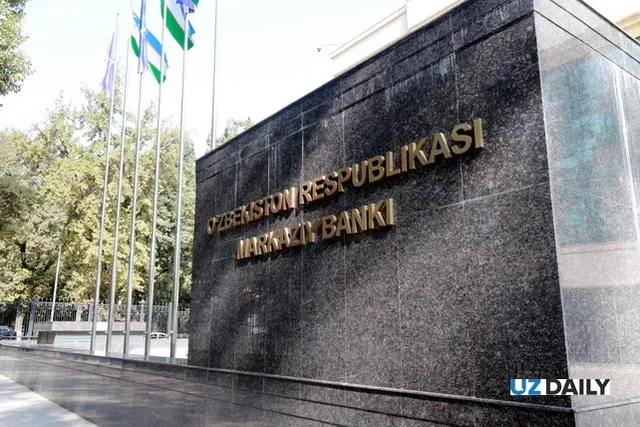
Tashkent, Uzbekistan (UzDaily.uz) — Completing the privatisation of Asaka Bank and Uzsanoatqurilishbank (SQB) would, for the first time, put most of Uzbekistan’s banking assets in private hands, Andi Aranitasi, Director and Head of the EBRD’s Uzbekistan office, said on 30 September at an event on the country’s economic outlook organised by the American Chamber of Commerce in Uzbekistan (AmCham).
Representatives of the IMF and Asian Development Bank who spoke at the same event linked the success of privatisation to reducing preferential lending and developing the capital market.
From Ipoteka Bank to Asaka Bank
The first major transaction in the banking sector was the sale of Ipoteka Bank to Hungary’s OTP Group, which acquired a controlling stake in the bank in 2023. The next, according to Andi Aranitasi, will be Asaka Bank, whose privatisation the EBRD has been working on with the authorities for around six years.
At the beginning of 2026, the Ministry of Economy and Finance, the EBRD and Asaka Bank signed an agreement on the key terms of the transaction, providing for the EBRD to acquire a 15% stake in the bank during 2026. In April, preparations were accelerated by a presidential decree: about US$95 million was allocated from the state budget to recapitalise the bank, while its debt to the Ministry of Economy and Finance of around 2 trillion soums may be converted into equity.
In parallel, work is under way with the International Finance Corporation (IFC) on the privatisation of SQB, which accounts for 11% of banking sector assets. The EBRD previously provided SQB with a US$50 million convertible loan. If the loan is converted into shares, the state’s stake in the bank will fall below 50%. The EBRD’s public project documentation confirms that the convertible financing was provided in support of SQB’s privatisation and could facilitate a reduction in state ownership below 50%.
Completion of these transactions, according to Andi Aranitasi, “will be a tectonic shift in Uzbekistan’s banking sector”, as most banking assets will, for the first time, be in private hands.
The EBRD’s Uzbekistan head explained that the banking sector reflects the state of the economy: when most of its assets are owned by private businesses, the private sector has more opportunities for growth.
Preferential lending
IMF Resident Representative in Uzbekistan Koba Gvenetadze, while confirming that work on privatising the two banks is under way, drew attention to an issue that a change in ownership does not resolve by itself.
This concerns preferential and targeted lending programmes implemented mainly through state-owned banks. Such programmes, he acknowledged, exist and will continue to exist, but their scale should decline as the economy grows.
Asel Aitkhozhina, EBRD Lead Regional Policy Specialist for Central Asia and Mongolia, explained why this matters. A high share of subsidised lending, characteristic of both Uzbekistan and Kazakhstan, weakens the impact of central bank interest-rate decisions on the economy.
Role of the capital market
ADB Senior Country Economist for Uzbekistan Sherzod Akbarov linked bank privatisation to the development of the capital market.
He described the IPO of the Uzbekistan National Investment Fund (UzNIF), the largest in the country’s history, as a positive signal. Following the offering in May on the London and Tashkent stock exchanges, the transaction amounted to US$691.5 million.
In the economist’s view, this paves the way for accelerated privatisation of other large state-owned enterprises.
The link between the two processes is direct: UzNIF was transferred a 40% stake in SQB, which, according to Fitch Ratings, improves the bank’s governance and risk management ahead of privatisation.
Timeline
Rapid transactions should not be expected, however. SQB was initially scheduled to be privatised by the end of 2025, but the sale was postponed, and Fitch’s base case does not expect it to take place before 2027.
The state currently owns nine banks: National Bank, Agrobank, Uzsanoatqurilishbank, Asaka Bank, Xalq Bank, Business Development Bank, Microcreditbank, Aloqabank and Turonbank. By 2030, the authorities plan to retain control over four of them.
The EBRD’s current country assessment likewise identifies privatisation of state-owned commercial banks as a key priority, noting that state-owned banks still account for most banking-system assets and that directed and preferential lending remains significant.