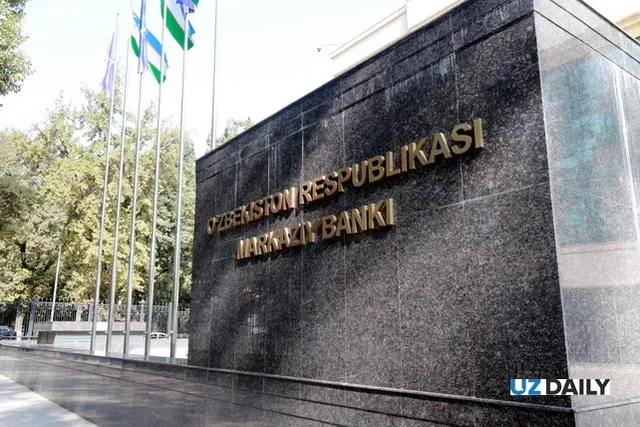
Tashkent, Uzbekistan (UzDaily.uz) — The Central Bank of Uzbekistan forecasts economic growth of 7–7.5% in 2027 and 6.5–7.5% in 2028–2029. Under the regulator’s baseline scenario, inflation is expected to decline to the 5% target in the second half of 2027 and remain close to that level over the following two years.
On 4 November 2026, the Central Bank’s board approved a draft concept of the Main Directions of Monetary Policy for 2027 and the 2028–2029 period. The document sets out macroeconomic forecasts, assesses potential risks and outlines measures to ensure price stability.
The baseline scenario assumes a gradual improvement in external and domestic economic conditions. In particular, the regulator takes into account the possible easing of geopolitical tensions and lower oil prices, as well as continued moderate economic growth among Uzbekistan’s main trading partners.
Domestic assumptions include keeping the overall fiscal deficit at around 3% of GDP, balanced expansion of lending and domestic demand, completion of regulated price reforms, and Uzbekistan’s accession to the World Trade Organization within the forecast period.
The Central Bank estimates that core inflation could fall to 4–5% in 2027. Factors expected to slow price growth include the fading direct impact of previous increases in energy and utility tariffs, easing external price pressures and an expansion in domestic supply.
The regulator intends to maintain tight monetary conditions in 2026–2027. According to the forecast, the real UZONIA rate in the money market will stand at around 6–7% in 2027. This policy is expected to contain domestic demand, lower inflation expectations and maintain the attractiveness of savings in the national currency.
A gradual easing of monetary conditions will be considered once the necessary conditions for a sustained stabilisation of inflation around the target have been established. If price pressures intensify or the secondary effects of price increases become more pronounced, tight policy may remain in place for longer.
The Central Bank has also assessed alternative scenarios involving a possible deterioration in external and domestic conditions. Key risks include significant depreciation of the currencies of major trading partners, a sharp rise in global oil and food prices, and faster lending growth amid increased competition in the banking sector. If these factors materialise, inflation could exceed the baseline forecast.
A separate section of the document focuses on improving the effectiveness of monetary policy. In 2027–2029, the Central Bank plans to develop a Monetary Policy Strategy and a roadmap for its implementation, improve liquidity management in the banking system, review the interest rate corridor and strengthen the role of UZONIA as a money market benchmark.
The plans also include developing liquidity provision and absorption instruments for Islamic banks in line with Sharia principles. The regulator intends to modernise its macroeconomic analysis and forecasting systems and expand the use of probabilistic models and alternative scenarios.
Other priorities include developing the money and financial markets, the derivatives market and instruments for hedging interest rate and foreign exchange risks, as well as improving liquidity in the domestic foreign exchange market.
The Central Bank also plans to prepare an overall monetary policy communication strategy. It is intended to increase transparency around key rate decisions, inflation forecasts and risk assessments, while strengthening the regulator’s accountability for achieving the inflation target.
The draft concept of the main monetary policy directions will be published on the Central Bank of Uzbekistan’s official website and revised to take into account the proposals received.