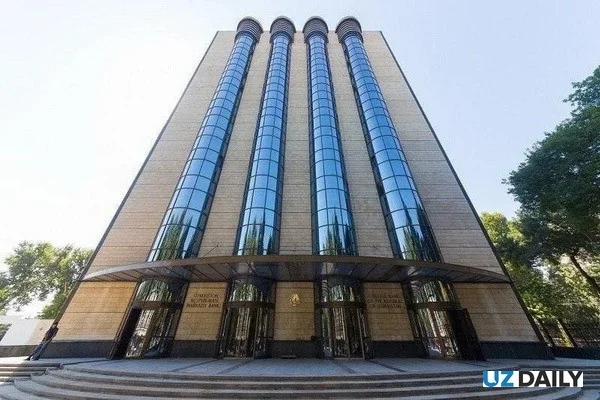
Tashkent, Uzbekistan (UzDaily.uz) — International rating agency Fitch Ratings affirmed Turonbank’s long-term issuer default ratings in foreign and local currencies at ‘BB-’ on 3 November 2026. The Outlook is Positive. The bank’s Viability Rating was affirmed at ‘b-’. Fitch Ratings reported this.
The bank’s long-term ratings reflect a moderate likelihood of support from the state. Uzbekistan’s sovereign rating is ‘BB’ with a Positive Outlook, while Turonbank’s Government Support Rating is ‘bb-’.
Fitch bases this assessment on the state’s ultimate ownership of the bank, its improved track record of capital injections and the authorities’ close involvement in its operations. The Positive Outlook on the bank’s ratings mirrors the outlook on Uzbekistan’s sovereign ratings.
The Government Support Rating is one notch below the sovereign rating. Fitch considers this to reflect Turonbank’s limited systemic and strategic importance to the state.
The authorities plan to privatise the bank in the long term. Turonbank is relatively small and does not have a clearly defined role in government policy.
The state has provided more active support to the bank over the past two years, although historically Turonbank received less new capital than most other state-owned banks in Uzbekistan. Fitch believes that support will remain available while the state retains a controlling stake.
The Viability Rating of ‘b-’ reflects the bank’s small franchise, vulnerable asset quality, moderate profitability and significant reliance on wholesale funding. At the same time, Fitch notes improvements in core capital adequacy and stable liquidity.
Fitch has also upgraded its assessment of the operating environment for banks in Uzbekistan to ‘b+’ from ‘b’, assigning a Stable Outlook instead of the previous Positive Outlook. The decision reflects progress in banking reforms over the past two years, particularly efforts to strengthen regulation and address legacy risks.
The country’s economy grew by 8.5% year on year in the first half of 2026. Fitch believes this should support growth in banks’ business and, over the medium term, their profitability and capital.
At the end of the third quarter of 2026, Turonbank accounted for 2% of the banking sector’s total assets. Most of its loans were issued to corporate clients and small and medium-sized businesses, which accounted for 77% of the loan portfolio at the end of 2025. A significant share of its funding comes from the state, accounting for 44% of the bank’s liabilities.
These funds are used to provide preferential loans under government programmes, including to state-owned companies, which account for 23% of the bank’s loans. The bank intends to increase its focus on commercial lending.
Non-performing loans accounted for 4% of the total portfolio at the end of 2025 and were almost fully covered by provisions.
Stage 2 loans, which Fitch considers high-risk, accounted for a further 12%. Agriculture, which the agency classifies as a problem sector, represented 17% of the loan portfolio. Foreign-currency loans accounted for 47%. These risks are mitigated by the fact that half of the foreign-currency loans were issued to the public sector and are backed by state guarantees.
The bank’s operating profit in 2025 amounted to 0.1% of risk-weighted assets, compared with 0.4% a year earlier. Fitch attributes this primarily to low margins on corporate lending, including preferential loans. The agency considers the bank’s loan-loss provisions unsustainably low, while its return on average equity remains at only a few per cent.
Fitch’s core capital ratio stood at 10% at the end of 2025, below the level reported by most Uzbek banks rated by the agency.
According to Fitch, the ratio had increased to around 12% by the third quarter of 2026, following a substantial capital injection from the state. The agency expects the bank to continue receiving capital from the authorities to support preferential lending.
Wholesale borrowings accounted for 31% of the bank’s liabilities at the end of 2025. These mainly comprise long-term loans from international financial institutions, which are generally renewed upon maturity. Funds from non-government clients accounted for just 25% of liabilities. Liquid assets represented 14% of total assets at the end of the third quarter of 2026. They were sufficient to fully cover external wholesale debt repayments falling due over the next 12 months.
The bank’s ratings could be downgraded following a downgrade of Uzbekistan’s sovereign ratings. A downgrade is also possible if Fitch concludes that the state’s willingness to support the bank has weakened. This could happen as the bank becomes more distant from the state during the privatisation process.
Another potential trigger would be the sale of the bank to a strategic investor with a rating below the sovereign rating or without a rating. The Viability Rating could be downgraded if the bank’s capital declines significantly, non-performing loans rise sharply or losses before loan-loss provisions increase.
An upgrade of Uzbekistan’s sovereign ratings could lead to a similar decision on Turonbank’s ratings. An exception would be a situation in which privatisation is likely to take the bank out of state ownership within the rating horizon. To secure an upgrade of its Viability Rating, the bank would need to achieve sustained improvements in asset quality and profitability, as well as strengthen its capital.
Fitch assigned Turonbank an ESG score of ‘4’ for the ‘Corporate Governance Structure’ factor.
The agency attributes this assessment to the authorities’ extensive involvement in the work of the bank’s supervisory board, business development and strategy, which negatively affects its credit profile.